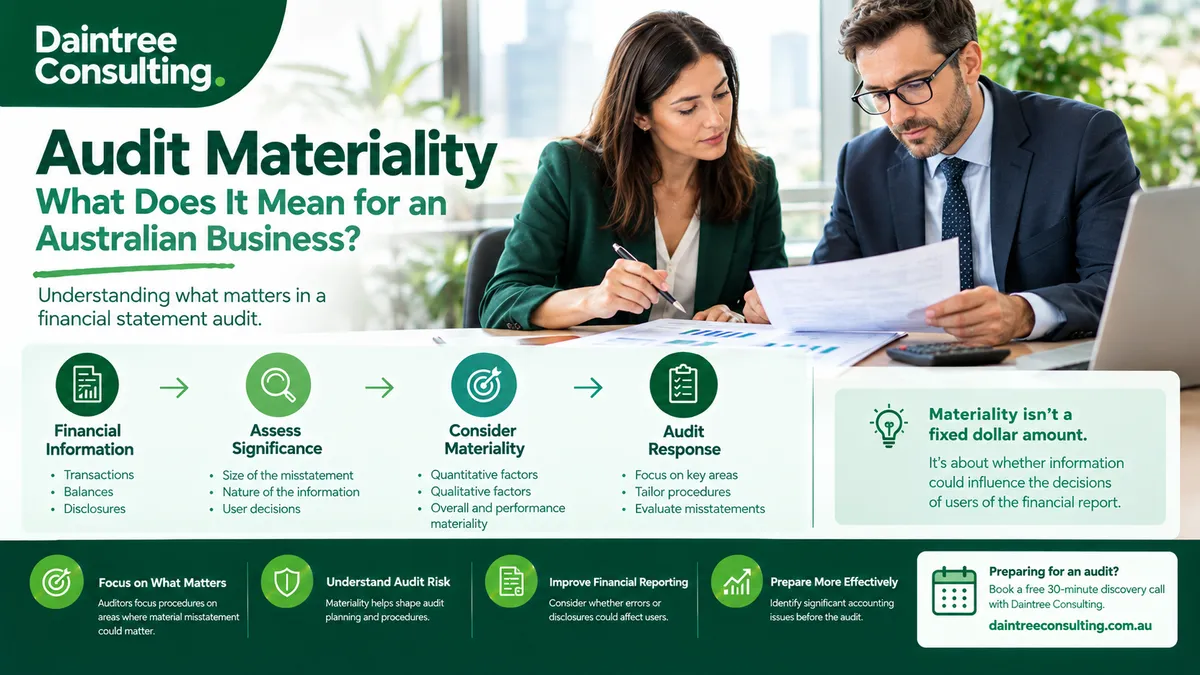
Audit Materiality Explained: What Does It Mean for an Australian Business?
When preparing for a financial statement audit, Australian business owners often hear the term “materiality”.
But what does audit materiality actually mean?
Want expert help? Daintree Consulting's audit and assurance services can take this off your plate. Book a free consultation.
In simple terms, audit materiality helps an auditor determine whether an error, omission, misclassification or disclosure issue could reasonably influence the decisions of users of the financial statements.
It is one of the concepts that helps auditors decide what matters, how much audit work is needed and how identified misstatements should be evaluated.
Under ASA 320 Materiality in Planning and Performing an Audit, auditors apply materiality when planning and performing an audit. They determine materiality for the financial report as a whole and, where appropriate, for particular classes of transactions, account balances or disclosures. Auditors also determine performance materiality to help reduce the risk that the aggregate of undetected and uncorrected misstatements exceeds the overall materiality level.
For Australian businesses, understanding audit materiality can make the audit process easier to understand.
It can also help management recognise why auditors may focus heavily on some financial statement areas while applying different procedures to others.
Quick answer: What is audit materiality in Australia?
Audit materiality is the auditor's assessment of how significant a misstatement or omission could be to users of the financial report.
A matter may be material if it could reasonably be expected to influence the economic decisions of users who rely on the financial statements.
Importantly, materiality is not simply a fixed dollar amount.
Auditors consider both:
The size of a potential misstatement
The nature of the matter
The circumstances surrounding it
The information needs of financial statement users
The potential effect on the financial report
ASA 320 makes clear that a misstatement can be material because of its nature or circumstances even when the amount is below the materiality level established during audit planning.
What does “material” mean in an audit?
The word material does not necessarily mean “large”.
In auditing, materiality is about whether information could matter to the people using the financial report to make economic decisions.
For example, suppose an Australian company has a small accounting error that does not significantly affect its financial position.
That may be less significant than an error of a similar or even smaller amount that:
Changes whether the company appears profitable
Causes a loan covenant to be breached
Changes an important performance measure
Affects a related-party disclosure
Hides a significant liability
Changes the classification of an important balance
Relates to fraud or suspected fraud
Results in an important disclosure being omitted
This is why auditors do not simply apply one universal “materiality percentage” to every issue.
Materiality involves professional judgement.
Why does audit materiality matter?
An auditor's job is not to check every transaction and eliminate every possible error.
A financial statement audit is designed to provide reasonable assurance that the financial report is free from material misstatement.
Materiality helps the auditor determine how to approach that objective.
It influences areas such as:
Audit planning
Risk assessment
Audit procedures
Sample selection
Evaluation of identified misstatements
Financial statement presentation
The eventual audit opinion
ASA 320 states that materiality is applied in planning and performing the audit and in evaluating the effect of identified and uncorrected misstatements.
This means materiality is relevant throughout the audit rather than being something considered only at the end.
How do auditors determine materiality?
There is no single materiality figure that applies to every Australian business.
The auditor considers the circumstances of the particular entity and the needs of users of its financial report.
A typical process involves several stages.
1. Understand the business
Before determining appropriate materiality, the auditor needs to understand the business and its financial reporting environment.
This can include considering:
The nature of the business
Its size
Its ownership structure
Its industry
Revenue and expense patterns
Assets and liabilities
Financing arrangements
Key stakeholders
Regulatory requirements
Financial performance
Significant transactions
Areas involving management judgement
This context matters because the same dollar amount can have very different significance for different businesses.
2. Consider who uses the financial statements
Materiality is ultimately connected to the decisions users make based on financial information.
Depending on the entity, users might include:
Shareholders
Directors
Investors
Lenders
Regulators
Members
Other stakeholders
The auditor considers what information is likely to matter to those users.
For example, a lender may be particularly interested in:
Debt levels
Liquidity
Profitability
Cash flow
Covenant compliance
A shareholder may focus more heavily on:
Profit
Assets
Returns
Performance
Changes in financial position
The relevance of particular information therefore depends partly on the circumstances and users of the financial report.
3. Establish overall materiality
ASA 320 requires the auditor to determine materiality for the financial report as a whole when establishing the overall audit strategy.
Where particular classes of transactions, account balances or disclosures could influence users even at amounts below the overall materiality level, the auditor may also establish separate materiality levels for those areas.
This is an important distinction.
There may not be just one number relevant to every part of the financial report.
For example, a particular disclosure may be important to users even though the monetary amount involved is relatively small.
4. Determine performance materiality
Auditors may also establish performance materiality.
Performance materiality is set below overall materiality.
Its purpose is to reduce the probability that the combined effect of uncorrected and undetected misstatements exceeds materiality for the financial report as a whole.
In practical terms, this gives the auditor a margin when planning audit procedures.
The auditor is not simply saying:
“Anything below this one number does not matter.”
Instead, performance materiality helps shape the nature, timing and extent of audit procedures.
Is audit materiality based on a percentage?
Sometimes quantitative materiality is calculated using a percentage applied to an appropriate benchmark.
However, Australian businesses should not assume that there is one mandatory percentage that auditors must use.
The appropriate benchmark and percentage involve professional judgement.
Possible benchmarks can vary depending on the circumstances of the entity.
For example, an auditor may consider measures relating to:
Revenue
Profit
Assets
Net assets
Expenses
Other relevant financial information
The appropriate benchmark depends on what is most relevant to the users of the financial report and the circumstances of the entity.
The AUASB's guidance explains that quantitative and qualitative factors both form part of the auditor's consideration of materiality.
Why the size of an error is not the only consideration
This is one of the most important concepts for business owners to understand.
A common assumption is:
“If the error is below materiality, the auditor will ignore it.”
That is not necessarily correct.
ASA 320 explains that circumstances can cause some misstatements to be considered material even when they are below the materiality level established for the financial report. The auditor considers both the size and nature of uncorrected misstatements.
This is why qualitative materiality matters.
What is qualitative materiality?
Qualitative materiality refers to circumstances where the nature or context of an item makes it significant.
Consider a few examples.
A related-party transaction
A transaction involving a related party may require particular disclosure.
Even if the amount is not particularly large, the nature of the relationship can make the information important to users.
A loan covenant
Suppose an error causes a company to appear to breach or comply with a financial covenant.
The amount of the error may be relatively small, but the effect on the user's understanding could be significant.
Management remuneration
An error affecting information about directors' or management remuneration may receive attention because of the nature of the disclosure.
Fraud
A relatively small fraudulent transaction can raise concerns beyond the dollar value involved.
The nature of the matter may indicate broader control or integrity issues.
Regulatory compliance
A financial statement matter connected to an important regulatory requirement may receive greater attention because of its circumstances.
These examples illustrate why materiality cannot be reduced to a simple calculation.
Quantitative vs qualitative materiality
A useful way to understand audit materiality is to think about two broad dimensions.
Quantitative
This considers the amount involved.
For example:
How large is the error?
How does it compare with the relevant benchmark?
How does it affect the financial statements?
Qualitative
This considers the nature and circumstances.
For example:
What does the error relate to?
Does it affect an important disclosure?
Does it involve a related party?
Could it affect a covenant?
Does it indicate fraud?
Does it change an important performance measure?
Auditors consider both.
The AUASB has specifically described materiality as involving both quantitative and qualitative factors.
Does materiality change during an audit?
It can.
ASA 320 requires the auditor to revise materiality for the financial report as a whole, and where applicable other materiality levels, if information discovered during the audit would have caused the auditor to determine a different amount initially.
This makes sense in practice.
An auditor may begin the audit with certain expectations about:
Revenue
Profit
Assets
Business performance
Significant transactions
During the audit, new information may change those expectations.
For example, the business may identify a significant transaction that was not known during planning.
The auditor may then need to reconsider the materiality assessment and related audit procedures.
Materiality is therefore not necessarily a number that is calculated once and never revisited.
How does materiality affect audit testing?
Materiality helps auditors determine the nature, timing and extent of audit procedures.
Higher-risk areas may require more persuasive evidence.
Materiality and risk are therefore connected.
For example, an auditor may decide that a particular account requires more detailed testing because:
It contains significant estimates
It has a higher risk of misstatement
It is important to users
It involves complex accounting
It has changed significantly
Previous errors have been identified
Materiality helps provide a framework for determining how much audit work is appropriate.
Does materiality mean auditors do not check small transactions?
No.
An audit does not work on the basis that every transaction below a particular dollar amount is automatically ignored.
Auditors use professional judgement, risk assessment, sampling and other procedures.
An individually small misstatement can also become important when combined with other misstatements.
This is one reason auditors accumulate identified misstatements during an audit.
ASA 450 requires auditors to accumulate misstatements identified during the audit other than those that are clearly trivial. Auditors then evaluate their effect on the audit and the financial report.
Can small errors become material when added together?
Yes.
Imagine a business has several separate errors:
$8,000 classification error
$12,000 expense cut-off error
$15,000 receivables adjustment
$10,000 inventory error
Each issue may appear relatively small when considered separately.
But the combined effect could be more significant.
ASA 450 requires auditors to consider identified misstatements and whether their aggregate effect could be material. The standard also requires the auditor to reconsider the audit strategy and plan when identified misstatements indicate that additional misstatements may exist or when accumulated misstatements approach materiality.
This is why businesses should not dismiss multiple small adjustments simply because each one looks insignificant on its own.
What is a clearly trivial misstatement?
Auditors may establish a threshold below which identified misstatements are considered clearly trivial and do not need to be accumulated under the requirements of ASA 450.
However, clearly trivial does not mean the same thing as “below materiality.”
There is a distinction between:
Overall materiality
Performance materiality
Clearly trivial amounts
These concepts serve different purposes within the audit.
Business owners should therefore avoid assuming that an amount below overall materiality is automatically irrelevant to the auditor.
How does materiality affect financial statement disclosures?
Materiality applies to more than numbers.
It can also affect presentation and disclosure.
For example, an omission or inaccurate disclosure may be important even if it does not involve a large monetary amount.
Potential areas include:
Accounting policies
Related-party transactions
Commitments
Contingencies
Financial instruments
Significant judgements
Accounting estimates
Events after the reporting date
Other disclosures required by the applicable reporting framework
The auditor considers whether the financial report, including its disclosures, is materially misstated.
This is important because a financial statement can contain technically correct numbers while still failing to provide information users reasonably need.
What does materiality mean for Australian business owners?
For management, the practical lesson is simple:
Do not manage the audit solely around a materiality threshold.
Instead, focus on preparing financial information that is:
Accurate
Complete
Consistent
Properly supported
Appropriately classified
Reconciled
Properly disclosed
Supported by relevant documentation
This makes it easier for the auditor to understand the financial report and investigate unusual or significant items.
What should businesses do before an audit?
Understanding materiality is useful, but good preparation goes further.
Reconcile key accounts
Make sure important balance-sheet accounts are reconciled before the audit begins.
This can include:
Bank accounts
Accounts receivable
Accounts payable
Loans
Payroll
GST accounts
Intercompany balances
Fixed assets
Review unusual transactions
Identify unusual or significant transactions before the auditor asks about them.
This might include:
Business acquisitions
Asset disposals
Large loans
Related-party transactions
Major contracts
Restructuring transactions
Significant investments
Document significant judgements
If management has made an important accounting judgement or estimate, document the reasoning and supporting information.
This can make audit discussions more efficient.
Check financial statement disclosures
Do not focus only on the numbers.
Review whether the required notes and disclosures are complete and consistent with the financial statements.
Investigate known errors
If management already knows about an error, it is generally better to identify and address it before the audit rather than waiting for the auditor to discover it.
Does an auditor set materiality for management?
No.
This is an important distinction.
The auditor determines audit materiality for the purposes of planning and performing the audit.
Management remains responsible for preparing the financial statements in accordance with the applicable financial reporting framework.
Management should not use the auditor's materiality assessment as a substitute for maintaining accurate accounting records and preparing appropriate financial statements.
For example, a business should not adopt the mindset:
“If it is below the audit materiality threshold, we do not need to record it properly.”
That is not the purpose of materiality.
Materiality is an audit concept used within the auditor's professional judgement and audit methodology.
Does materiality determine whether an audit is required?
No.
This is another common misunderstanding.
Audit materiality does not determine whether an Australian business is legally required to have an audit.
Whether an entity requires an audit depends on its entity type, applicable legislation, reporting obligations and individual circumstances.
Materiality is instead concerned with the significance of potential misstatements within the financial report being audited.
These are two separate questions:
Question 1: Does the entity need an audit?
Question 2: During that audit, what matters could be material to users of the financial report?
Do not confuse the two.
How does materiality relate to the audit opinion?
At the end of the audit, the auditor considers identified and uncorrected misstatements and their effect on the financial report.
ASA 450 addresses the auditor's evaluation of identified and uncorrected misstatements. The auditor's evaluation feeds into the conclusion about whether the financial report as a whole is free from material misstatement.
If identified matters are material, they can affect the auditor's conclusions and potentially the audit opinion, depending on the circumstances.
This is one reason management should take audit adjustments and identified financial reporting issues seriously.
Why Australian businesses should understand audit materiality
For a business owner, audit materiality may initially sound like technical accounting terminology.
But it has practical implications.
It explains why an auditor may:
Focus on certain accounts
Ask detailed questions about particular transactions
Request additional evidence
Test some areas more extensively than others
Ask management to correct an error
Investigate a disclosure that appears relatively small
Reconsider audit procedures as new information emerges
Understanding the concept can make those requests easier to interpret.
It also reinforces an important point:
An audit is not simply a search for large numerical errors.
Auditors consider the size, nature and circumstances of matters when determining whether they could influence users of the financial report.
Audit materiality example
Consider an Australian company with a significant bank loan.
During the audit, the auditor identifies a relatively small accounting error.
On its own, the amount might not appear significant compared with the company's total revenue or assets.
However, the error causes the company's reported financial position to cross a threshold relevant to its loan agreement.
The issue may therefore deserve greater attention than its dollar value alone would suggest.
The example illustrates why materiality is not purely mathematical.
The context and potential effect on users can matter.
What should management take away from audit materiality?
There are five practical lessons worth remembering.
1. Materiality is not a universal percentage
The appropriate materiality assessment depends on the circumstances of the entity and professional judgement.
2. Smaller does not always mean immaterial
The nature and circumstances of a matter can make it significant even when the amount is relatively small.
3. Multiple small errors can add up
Auditors consider the aggregate effect of identified misstatements.
4. Disclosures matter too
Materiality is not limited to the amounts appearing in the primary financial statements.
5. Good records still matter
Businesses should maintain accurate, complete and well-supported accounting records regardless of the auditor's materiality assessment.
How Daintree Consulting can help with audit preparation
Preparing for an audit is easier when financial records and supporting information are organised before the auditor begins testing.
Daintree Consulting can support Australian businesses with Audit & Assurance requirements and audit readiness, including:
Financial statement audit preparation support
Account reconciliations
Audit schedules
Supporting documentation
Balance-sheet review
Financial reporting support
Internal-control and process reviews
Preparation of responses to auditor information requests
Identification of potential accounting issues before the audit
Coordination of information required during the audit process
The objective is not to influence the auditor's independent judgement.
It is to help management ensure that the financial information, records and supporting documentation are organised and ready for the audit.
If your business has an upcoming audit and you want to understand what needs to be prepared, Daintree Consulting can help you get the financial records and supporting information organised.
Book a free 30-minute discovery call with Daintree Consulting.
Frequently Asked Questions
What is audit materiality in Australia?
Audit materiality is the auditor's assessment of the level at which a misstatement or omission could reasonably be expected to influence the economic decisions of users of the financial report.
Is audit materiality a fixed dollar amount?
No.
The auditor determines materiality using professional judgement and considers the circumstances of the entity, relevant users and financial information. Materiality may also be determined for particular classes of transactions, balances or disclosures.
What is performance materiality?
Performance materiality is an amount set below materiality for the financial report as a whole, or for particular classes of transactions, balances or disclosures where applicable. It helps reduce the risk that undetected and uncorrected misstatements collectively exceed the relevant materiality level.
Can an error below materiality still matter?
Yes.
The nature and circumstances of a misstatement can cause it to be considered material even if the amount is below the overall materiality level.
Can several small errors become material?
Yes.
Auditors consider identified misstatements individually and in aggregate. Multiple smaller misstatements can collectively have a material effect on the financial report.
Does materiality apply to disclosures?
Yes.
Materiality can apply to financial statement disclosures as well as amounts recorded in the financial statements.
Does management determine audit materiality?
No.
The auditor determines materiality for the purposes of planning and performing the audit. Management remains responsible for preparing the financial statements.
Does audit materiality determine whether my business needs an audit?
No.
Whether an audit is required is a separate question determined by the entity's circumstances and applicable legal and reporting requirements.
Does materiality affect the audit opinion?
It can.
The auditor evaluates identified and uncorrected misstatements when forming conclusions about whether the financial report is materially misstated. Depending on the circumstances, material misstatements can affect the auditor's report.
How can I prepare my business for an audit?
Start by reconciling key accounts, reviewing significant and unusual transactions, organising supporting documentation, checking financial statement disclosures and documenting significant accounting judgements and estimates.
Talk to Daintree about your audit
Our ex-Big 4 team gives clear, senior-reviewed advice so you can act with confidence.
Book a free consultation →
Or explore our audit and assurance services.
