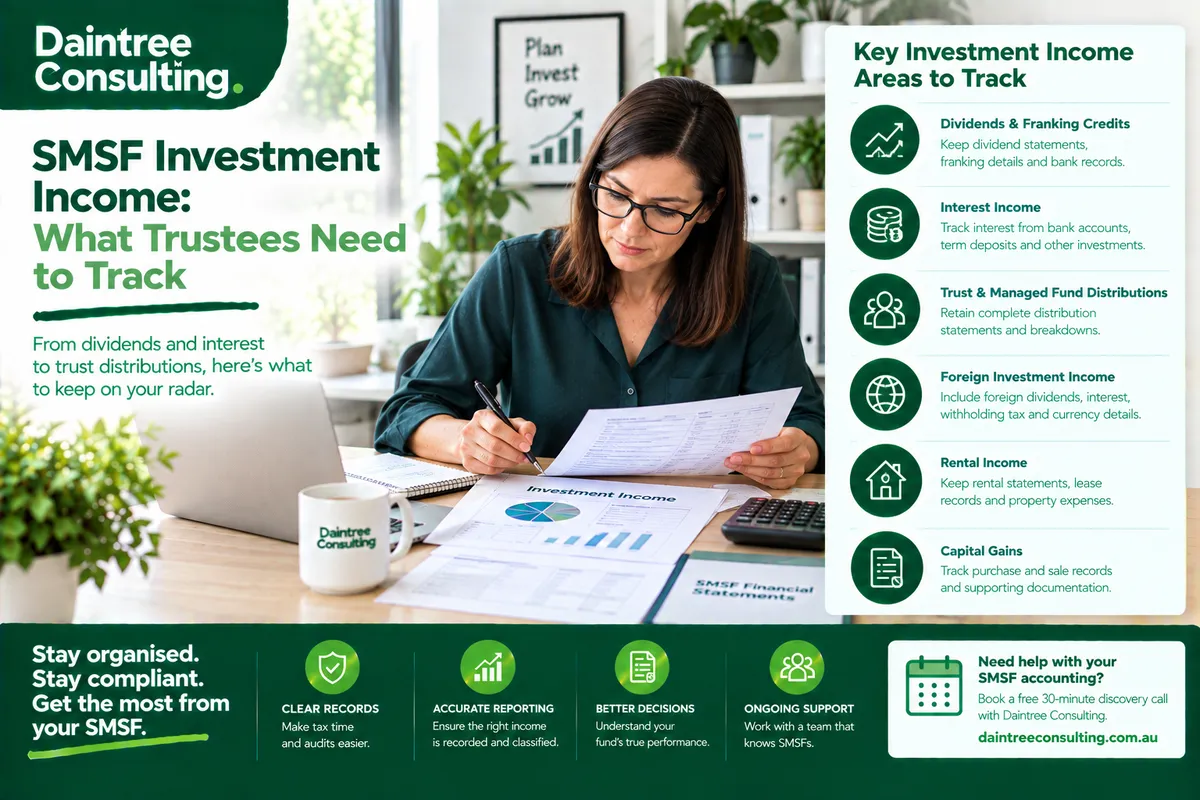
SMSF Investment Income: What Trustees Need to Track
For many self-managed super funds, investment income is one of the most important parts of the annual accounting process.
An SMSF may receive dividends from Australian shares, interest from bank accounts and fixed-income investments, distributions from managed funds or trusts, rental income from property, and income from other investments.
Want expert help? Daintree Consulting's SMSF accounting services can take this off your plate. Book a free consultation.
Keeping track of that income is not simply a matter of checking how much money entered the SMSF bank account.
Trustees need to make sure the fund's investment income is properly recorded, supported by appropriate documentation and correctly reflected in the SMSF's financial statements and annual reporting.
This becomes particularly important where the fund receives franked dividends, trust distributions, foreign investment income or income connected with pension interests.
The ATO's SMSF audit guidance specifically identifies income records such as bank statements, income statements, trust distributions and dividend statements as evidence that auditors may review.
For trustees, the practical question is:
What investment income should an SMSF track, and what records should be kept?
What is SMSF investment income?
SMSF investment income generally refers to income earned by the fund's investments during the financial year.
Depending on the fund's portfolio, this can include:
Dividends from Australian shares
Franked dividends
Unfranked dividends
Interest from bank accounts
Interest from investments
Distributions from managed funds
Trust distributions
Rental income
Foreign investment income
Other income generated by fund investments
The exact accounting and tax treatment depends on the nature of the investment and the circumstances of the fund.
Investment income should therefore be recorded according to the underlying transaction and supported by appropriate documentation.
The SMSF's accounting records need to explain the fund's transactions and financial position, while trustees must also retain relevant records for the required periods.
Why is investment income important in SMSF accounting?
Investment income affects more than the fund's bank balance.
It can flow through to:
The SMSF's financial statements
The fund's income calculation
Tax reporting
Franking credit calculations
Investment performance reporting
Member accounts
Pension and accumulation calculations
The fund's annual audit
The SMSF annual return
This means an income transaction needs to be recorded accurately and connected to the underlying investment.
For example, if an SMSF receives a dividend payment, the accounting records may need to reflect more than the cash received.
The fund may also need to account for:
The dividend amount
Any franking credit
The investment that generated the income
The date of the transaction
Any relevant withholding or foreign tax information
The appropriate tax treatment
Supporting dividend documentation
The ATO's SMSF annual return instructions separately identify franked dividends and dividend franking credits, demonstrating why trustees should retain the relevant information rather than relying solely on the bank transaction.
What should SMSF trustees track?
A practical SMSF investment income process should track each source of income throughout the financial year.
1. Dividends from Australian shares
If the SMSF owns Australian shares, it may receive dividend payments during the year.
Trustees should retain the relevant dividend statements and make sure the accounting records agree with the underlying investment activity.
For each dividend, it can be useful to track:
Company name
Number of shares held
Dividend payment date
Dividend amount
Franked amount
Unfranked amount
Franking credit
Any withholding amount
Bank receipt
Supporting dividend statement
The ATO's SMSF auditor checklist specifically identifies dividend statements as documentation auditors may inspect when verifying listed share investments.
Why is the dividend statement important?
The amount deposited into the SMSF's bank account may not tell the complete story.
A dividend statement can contain information needed to correctly account for the income and any associated franking credit.
For this reason, trustees should avoid treating the bank statement as the only source of information for dividend accounting.
2. Franked dividends and franking credits
Franking credits are an important part of SMSF investment income where the fund receives franked dividends.
A franked dividend can include a franking credit representing tax paid by the company before the dividend was distributed.
For SMSF accounting and tax reporting, the dividend amount and associated franking credit need to be identified correctly.
The ATO's current SMSF annual return instructions provide separate reporting treatment for franked dividends and dividend franking credits.
The ATO also notes that entitlement to a franking credits tax offset can depend on applicable requirements, including the holding period rule and related payment rule.
This is one reason trustees should retain the original dividend statements rather than trying to reconstruct franking information at year-end.
What should trustees keep?
For franked dividends, retain:
Dividend statements
Broker records
Shareholding records
Bank statements
Relevant tax information
Records supporting the acquisition and disposal of shares where applicable
The accounting records should then reconcile to the underlying documentation.
3. Interest income
Interest is another common source of SMSF investment income.
An SMSF may receive interest from:
Bank accounts
Term deposits
Fixed-interest investments
Certain debt investments
Other interest-bearing assets
Trustees should ensure that interest received during the financial year is captured in the accounting records.
Bank statements are an important source of evidence, but trustees should also consider whether there are accrued amounts or other investment information that needs to be reflected in the financial statements.
At year-end, the accounting records should be reviewed to determine whether the reported interest agrees with available statements and supporting information.
4. Managed fund and trust distributions
SMSFs can also receive distributions from trusts and managed investments.
These can be more complicated than straightforward bank interest or dividends.
A distribution may contain several components, such as:
Income
Franked distributions
Capital gains
Foreign income
Tax credits
Other amounts
The amount deposited into the SMSF bank account may therefore not represent the complete tax or accounting information associated with the distribution.
Trustees should retain the relevant distribution statement and provide it to the SMSF accountant.
The ATO's SMSF auditor checklist identifies trust distribution statements, bank statements and evidence of distributions paid or owed as relevant documentation for audit purposes.
A common mistake
One common problem is recording the cash received as the entire investment income amount without reviewing the distribution statement.
That can result in important components being missed or incorrectly classified.
The better approach is to provide the complete distribution information to the person preparing the SMSF accounts and tax return.
5. Foreign investment income
Some SMSFs hold investments outside Australia.
Foreign investment income may introduce additional information requirements, including:
Foreign dividends
Foreign interest
Foreign withholding tax
Foreign distributions
Currency conversion
Foreign tax offsets where applicable
Trustees should retain the original statements from the investment provider or broker.
This is particularly important because foreign income may need to be converted into Australian dollars and reported differently depending on its nature.
Rather than trying to calculate foreign investment income from bank deposits alone, trustees should retain the underlying investment statements.
6. Rental income from SMSF property
Where an SMSF owns an investment property, rental income can also form part of the fund's investment income.
The records may need to include:
Rental statements
Lease agreements
Rent received
Property management statements
Expenses
Repairs and maintenance
Rates
Insurance
Other relevant property costs
The treatment of property income and expenses depends on the circumstances and applicable tax and superannuation rules.
Trustees should also ensure that property transactions remain consistent with the fund's investment strategy and other SMSF requirements.
7. Investment income that has not yet been received
Trustees should not assume that only cash received in the SMSF bank account matters.
There can be situations where investment income has been declared or accrued but has not yet been received at year-end.
Examples could include:
Dividends declared but unpaid
Interest accrued
Trust distributions owed to the SMSF
Rental income outstanding
The appropriate accounting treatment depends on the circumstances and applicable accounting and tax requirements.
This is another reason why year-end SMSF accounting should involve a review of investment statements and supporting records rather than simply reconciling the bank account.
SMSF investment income and capital gains are not the same thing
Another important distinction is between investment income and capital gains.
Suppose an SMSF owns shares.
The fund may receive:
Dividend income while holding the shares.
It may also later make a:
Capital gain or capital loss when the shares are sold.
These are different transactions and need to be tracked separately.
For example, if an SMSF receives $5,000 in dividends and later sells shares for a $20,000 capital gain, the $5,000 dividend and $20,000 capital gain are not simply one pool of "investment income".
The underlying investment records should allow the accountant to identify each component correctly.
This is why purchase records, sale contracts, broker reports and dividend statements should all be retained.
What records should an SMSF keep for investment income?
A well-organised SMSF investment file should generally contain documentation supporting the fund's investments and related income.
Depending on the portfolio, this could include:
Bank statements
Dividend statements
Managed fund distribution statements
Trust distribution statements
Broker statements
Investment portfolio reports
Share purchase contracts
Share sale contracts
Term deposit statements
Interest statements
Rental statements
Property management reports
Foreign investment statements
Evidence of withholding tax
Capital gains information
Investment valuation information
Relevant trustee minutes
Investment strategy documentation
The exact records required depend on the SMSF's investments and circumstances.
The ATO states that SMSFs must maintain proper and accurate records, including accounting records explaining the fund's transactions and financial position.
How does SMSF investment income affect the annual audit?
SMSFs generally undergo an annual audit as part of their compliance obligations.
The auditor needs evidence that the financial statements and relevant compliance matters have been appropriately supported.
Investment income can therefore become an important part of the audit file.
The ATO's auditor checklist includes checking whether all income has been appropriately recorded and identifying evidence such as:
Bank confirmations
Bank statements
Income statements
Trust distributions
Dividends
Ledger transactions
The auditor may also examine evidence supporting the ownership, valuation and investment returns of the SMSF's assets.
This means incomplete investment records can create additional questions during the audit.
What happens if dividend records are incomplete?
Missing investment documentation can create several problems.
For example, if an SMSF's accounting records show a dividend payment but the corresponding dividend statement cannot be located, the accountant may need to obtain additional information before completing the accounts.
Similarly, if a managed fund distribution is recorded as a single amount but the distribution statement contains several tax components, additional work may be required to determine the correct treatment.
This can delay the annual accounting and audit process.
In some circumstances, incomplete records may also make it harder to verify:
Income
Asset ownership
Franking credits
Capital gains
Taxable income
Investment valuations
Foreign tax information
Good record keeping is therefore not simply an administrative exercise.
It helps create a clear audit trail from the investment transaction through to the SMSF's financial statements and annual return.
How should trustees organise SMSF investment records?
A simple system can make year-end accounting significantly easier.
Keep records by investment
Consider maintaining a digital folder or accounting record for each major investment category.
For example:
Australian shares
Dividend statements
Broker statements
Purchase records
Sale records
Managed funds
Distribution statements
Annual tax statements
Investment statements
Cash and term deposits
Bank statements
Interest statements
Term deposit documentation
Property
Rental statements
Lease documents
Property expenses
Valuation information
This makes it easier to identify missing information before the accounts are prepared.
Reconcile investment income throughout the year
Trustees do not necessarily need to wait until the end of the financial year to identify discrepancies.
Regular reconciliation can help identify:
Missing dividends
Incorrectly recorded income
Duplicate transactions
Unallocated bank receipts
Missing distribution statements
Differences between broker records and accounting records
The more frequently these issues are identified, the less likely they are to become a major year-end problem.
Keep investment ownership records up to date
Investment income should also be considered alongside the underlying investment.
For example, if an SMSF owns listed shares, the records should support both:
The investment itself
and
The income generated by that investment.
The ATO's audit guidance indicates that auditors may examine evidence of ownership, investment returns and supporting documents such as share certificates, dividend statements and purchase or sale records.
This provides an important practical lesson for trustees:
Do not keep income records separately from investment records without a clear connection between them.
What about SMSFs paying pensions?
Investment income can become more complex when an SMSF has members receiving retirement-phase income streams.
Depending on the fund's circumstances, income may need to be considered in relation to exempt current pension income (ECPI).
The ATO's SMSF auditor checklist specifically requires auditors to consider whether any ECPI claimed is appropriate and whether the relevant calculations and supporting documentation are correct.
The ATO's SMSF annual return instructions also show that income amounts included as ECPI can need to be identified separately in the annual return.
Trustees should therefore avoid assuming that all SMSF investment income is automatically taxed in exactly the same way.
The fund's member structure, pension arrangements, investment structure and accounting circumstances can all affect the treatment.
What trustees should check before year-end SMSF accounting
Before sending records to an SMSF accountant, trustees can work through a simple checklist.
Investment income
Have all dividends, interest and distributions been identified?
Dividend statements
Are statements available for all dividends received?
Franking credits
Have franking credit details been retained?
Trust distributions
Are complete distribution statements available?
Foreign investments
Have foreign income and withholding tax information been provided?
Capital transactions
Are purchase and sale records available for investments that were disposed of?
Bank reconciliation
Do investment income transactions agree with the SMSF bank records?
Investment ownership
Can the fund demonstrate ownership of its investments?
Valuations
Is the information required to support year-end investment valuations available?
Pension arrangements
If members receive pensions, has the relevant information been provided for the SMSF accounting and ECPI calculations?
Investment strategy
Have trustee decisions and investment strategy records been maintained appropriately?
The ATO states that SMSF trustees are responsible for preparing financial statements, arranging the annual audit, lodging the annual return and keeping accurate records.
Common SMSF investment income mistakes
Several issues can make SMSF accounting more difficult.
Recording only the cash received
A bank transaction may not contain all the information required for correct accounting and tax reporting.
Losing dividend statements
The statement may contain information about franked and unfranked amounts and franking credits that cannot be reliably reconstructed from the bank transaction alone.
Treating trust distributions as simple cash income
A distribution statement may contain multiple components requiring separate treatment.
Mixing investment income with capital gains
Dividends and capital gains arise from different transactions and should be tracked accordingly.
Not providing foreign investment information
Foreign income can require additional information about currency and withholding tax.
Waiting until the annual audit to find missing documents
Missing records are easier to resolve when identified during the year rather than after the accounts have already been prepared.
Failing to reconcile investment records
Differences between broker reports, investment statements, bank transactions and accounting records can create unnecessary year-end work.
How SMSF accounting helps trustees stay organised
Professional SMSF accounting is not simply about producing an annual set of financial statements.
A properly maintained accounting process can help trustees keep track of:
Investment income
Contributions
Pension payments
Investment transactions
Asset values
Member balances
Fund expenses
Tax information
Audit documentation
It also creates a clearer connection between the SMSF's underlying transactions and its annual reporting obligations.
For trustees with multiple investments, regular accounting can become particularly useful because the number of statements, transactions and tax components can increase quickly.
How Daintree Consulting can help with SMSF investment accounting
Managing SMSF investment income requires more than recording deposits into the fund's bank account.
Daintree Consulting can support trustees with SMSF accounting and the records required to keep the fund's financial information organised.
Support can include:
SMSF accounting
Annual financial statements
Investment transaction records
Dividend and distribution accounting
Investment income tracking
Contributions and pension accounting
Audit-file preparation
Coordination with the SMSF auditor
Annual return support
Reconciliation of fund accounts
Organising supporting documentation
The objective is to give trustees clearer financial records and make the annual accounting and audit process more organised.
If your SMSF holds shares, managed funds, property or multiple investments, having the underlying income and investment records properly maintained can make a significant difference at year-end.
Need help keeping your SMSF investment records organised?
Daintree Consulting provides SMSF Accounting support for trustees who need accurate records, organised investment information and practical assistance with annual SMSF reporting.
Book a free 30-minute discovery call with Daintree Consulting to discuss your SMSF accounting requirements.
Frequently Asked Questions
What is SMSF investment income?
SMSF investment income is income generated by the fund's investments. Depending on the portfolio, this can include dividends, interest, trust or managed fund distributions, rental income and foreign investment income.
Do SMSFs pay tax on dividends?
The tax treatment of dividend income depends on the SMSF's circumstances and the applicable superannuation and tax rules. Franked dividends can also involve franking credits, which need to be correctly recorded and reported.
What records should an SMSF keep for dividends?
Trustees should retain dividend statements, broker or investment records, bank records and information showing the relevant dividend and franking credit details.
What are franking credits in an SMSF?
Franking credits generally represent tax paid by an Australian company before a franked dividend is distributed. An SMSF's entitlement to use associated franking credits depends on applicable requirements.
Does an SMSF need to record investment income separately from capital gains?
Yes. Dividends, interest, distributions and capital gains arise from different transactions and can have different accounting and tax treatment.
What happens if an SMSF receives a managed fund distribution?
The trustee should retain the complete distribution statement. The distribution may contain several components, such as income, capital gains, franked distributions or foreign income, which may require different treatment.
Why do SMSF auditors ask for dividend statements?
Dividend statements provide evidence supporting the fund's investment income and can contain information needed to verify dividend amounts and franking credits.
How long should SMSF records be kept?
The required retention period depends on the type of record. The ATO's SMSF guidance states that some records need to be kept for at least five years, while certain records, such as trustee meeting minutes and decisions, need to be retained for at least ten years.
How can trustees make SMSF accounting easier?
Keep investment statements, dividend statements, broker reports, bank statements and other supporting documents organised throughout the year. Regular reconciliation can also help identify missing or incorrect information before year-end.
Talk to Daintree about your SMSF accounts
Our ex-Big 4 team gives clear, senior-reviewed advice so you can act with confidence.
Book a free consultation →
Or explore our SMSF accounting services.
