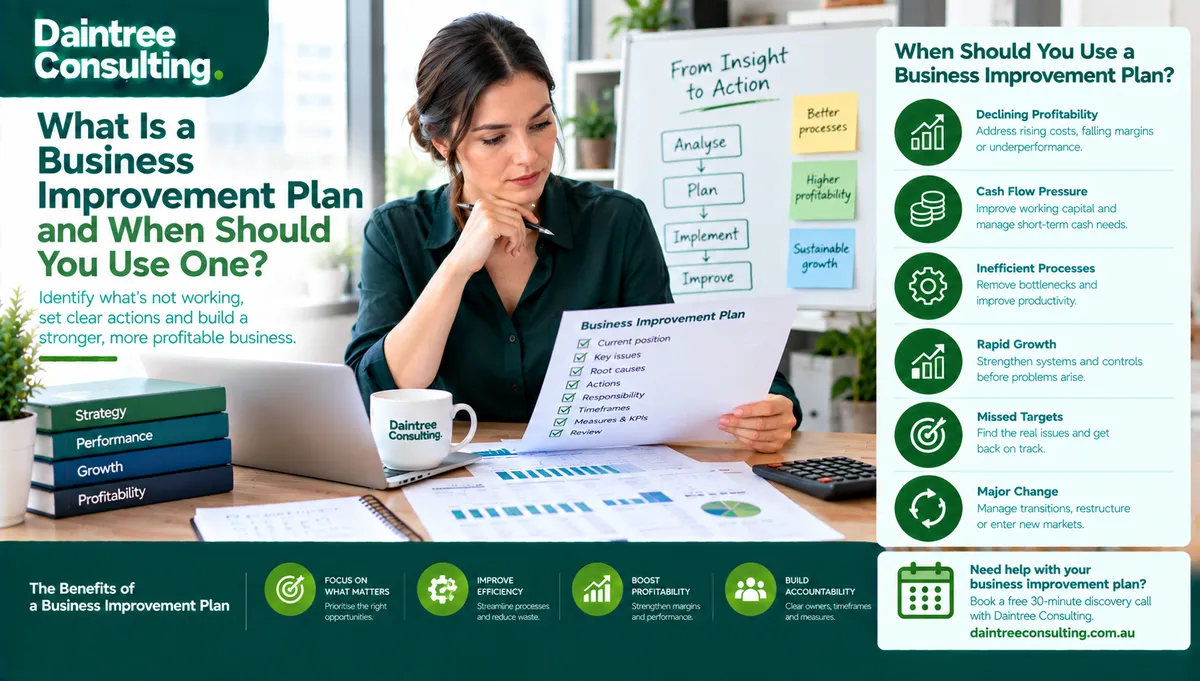
What Is a Business Improvement Plan and When Should You Use One?
A business does not always need a major turnaround to benefit from a more structured approach to improvement.
Sometimes the issue is straightforward: costs are rising, cash flow is tightening, margins are falling, staff productivity is inconsistent, or business processes are becoming harder to manage as the company grows.
Want expert help? Daintree Consulting's business advisory services can take this off your plate. Book a free consultation.
The challenge is knowing what to fix first.
This is where a business improvement plan can help.
A business improvement plan provides a structured way to identify areas of underperformance, decide what needs to change and turn those priorities into specific actions.
It can be used by a small business experiencing operational pressure, a growing business that has outgrown its current processes, or an established company looking to improve profitability and performance.
The important point is that a business improvement plan should not simply become another document sitting in a folder.
It should help management answer three practical questions:
What needs to improve? What are we going to do about it? How will we know whether it is working?
Quick answer: What is a business improvement plan?
A business improvement plan is a structured plan that identifies areas of a business that need improvement and sets out the actions, responsibilities, priorities and measures needed to address them.
Depending on the business, the plan may focus on:
profitability
cash flow
costs
operational efficiency
sales performance
customer retention
staffing
financial controls
business processes
reporting
working capital
technology
risk management.
A good plan connects the problem to the action.
For example, instead of saying:
“Improve cash flow.”
a more useful plan might identify slow customer payments as a contributing issue, establish a target for reducing outstanding receivables, assign responsibility for follow-up and review the result each month.
That makes the improvement measurable rather than theoretical.
Why Do Businesses Use Improvement Plans?
Running a business creates constant competing priorities.
An owner may know that something is not working particularly well but still struggle to determine where to start.
A business improvement plan can create structure around that problem.
It can help management:
identify the most important issues
separate symptoms from underlying problems
prioritise improvement opportunities
assign responsibility
establish measurable targets
set realistic timeframes
monitor progress
make better use of financial information
create accountability.
This can be particularly useful when a business has several issues at the same time.
For example, falling profit may not be caused by one problem.
It could involve a combination of:
higher supplier costs
inefficient labour allocation
pricing that has not kept pace with costs
excessive overheads
poor stock management
slow collections
underperforming products or services.
A business improvement plan provides a framework for investigating these issues instead of responding to each one separately.
When Should You Use a Business Improvement Plan?
There is no single point in a business's lifecycle when an improvement plan becomes necessary.
It can be useful whenever there is a meaningful gap between where the business is and where management wants it to be.
Here are some common situations.
1. Profitability has declined
Revenue can increase while profitability gets worse.
This can happen when costs rise faster than sales, margins decline or the business takes on additional overheads without generating sufficient additional contribution.
A business improvement plan can help break the problem down.
Management might review:
gross margin
operating expenses
labour costs
pricing
product or service profitability
customer profitability
overheads
revenue mix.
The objective is to understand what is affecting profitability and establish specific actions rather than simply telling the team to “reduce costs”.
2. Cash flow is becoming difficult to manage
A profitable business can still experience cash-flow pressure.
Money may be tied up in unpaid invoices, inventory, work in progress or other working-capital requirements.
If cash flow is becoming unpredictable, an improvement plan could focus on:
debtor collection
payment terms
supplier arrangements
inventory management
cash-flow forecasting
billing processes
working-capital requirements.
The plan should identify what is causing the pressure and what management can realistically change.
3. Business processes are becoming inefficient
Processes that worked when a business was small may become inefficient as transaction volumes and staff numbers increase.
For example, a business might still rely on:
manual spreadsheets
duplicated data entry
informal approval processes
disconnected software
unclear responsibilities
inconsistent procedures.
These problems can consume management time and increase the risk of errors.
An improvement plan can document which processes need attention, why they matter and what changes should be made.
4. The business is growing quickly
Growth can create its own problems.
More customers, employees, suppliers and transactions can put pressure on financial and operational systems.
A business may suddenly need better:
management reporting
cash-flow forecasting
budgeting
financial controls
staff processes
inventory management
customer systems
financial oversight.
A business improvement plan can help management strengthen these areas before they become significant constraints on growth.
5. Performance is below expectations
Perhaps the business has established targets but is consistently missing them.
The problem could relate to:
sales
margins
customer retention
project profitability
utilisation
expenses
debtor days
cash conversion.
Rather than simply changing the target, management can use an improvement plan to investigate why the current result is falling short.
6. The business has experienced a major change
A business improvement plan can also be useful after a significant change.
Examples include:
a change in ownership
entering a new market
losing a major customer
acquiring another business
introducing new technology
restructuring the team
changing suppliers
launching a new product or service.
The plan can provide a framework for managing the transition and identifying areas that need attention.
What Should a Business Improvement Plan Include?
There is no universal template.
The contents should reflect the business and the problem being addressed.
However, a practical business improvement plan will usually include several key components.
1. Current position
Start with an honest assessment of where the business is now.
This might include:
revenue
gross profit
net profit
cash position
receivables
payables
key expenses
operational performance
relevant KPIs.
Financial information is particularly useful because it can help quantify the problem.
For example, “costs feel too high” is difficult to manage.
“Operating expenses have increased by 18% while revenue has increased by 6%” provides a clearer starting point for investigation.
2. Problems and improvement opportunities
Identify the areas that need attention.
Not every problem needs to become a priority.
A useful improvement plan distinguishes between:
Critical issues — problems that could materially affect the business if not addressed.
Important improvements — areas where performance could be meaningfully improved.
Lower-priority opportunities — useful changes that can be addressed when resources allow.
This prevents the business from creating a long list of initiatives that nobody has the capacity to complete.
3. Root causes
One of the most important parts of a business improvement plan is identifying why the problem exists.
For example:
Problem: Profit margin has fallen.
Possible causes could include:
supplier price increases
outdated pricing
excessive discounting
inefficient labour allocation
higher overheads
changes in the sales mix.
The improvement plan should address the underlying cause rather than simply the visible symptom.
4. Actions
Each priority should lead to a practical action.
For example:
Issue: Customer invoices are being paid slowly.
Action: Review payment terms, establish a formal follow-up process and introduce weekly receivables monitoring.
The action should be specific enough that someone knows what needs to happen.
5. Responsibility
Someone should own each action.
This might be:
the business owner
finance manager
operations manager
sales manager
HR team
external adviser
another member of the leadership team.
Without clear ownership, improvement initiatives can easily become everyone's responsibility and therefore nobody's responsibility.
6. Timeframes
Set a realistic timeframe for each action.
Some changes may take days.
Others may require several months.
For example:
review pricing within 30 days
establish a monthly management reporting process within 60 days
reduce overdue receivables over the next quarter
implement a new operational process within six months.
Timeframes create a basis for follow-up.
7. Measures and KPIs
You need a way to determine whether the improvement is working.
Depending on the business, this could involve:
gross margin
net profit margin
revenue growth
debtor days
cash balance
labour utilisation
overhead percentage
customer retention
sales conversion
inventory turnover
project margins.
The right KPI depends on the problem.
A business improvement plan should avoid measuring everything simply because the data is available.
8. Review process
The final component is ongoing review.
An improvement plan should be revisited regularly to determine:
what has been completed
what has not progressed
what results have been achieved
what remains a problem
whether priorities have changed
whether additional action is required.
This turns the plan into a management tool rather than a one-off exercise.
Business Improvement Plan Example
Consider a business that has experienced declining profit despite steady revenue.
Management reviews its financial information and identifies three contributing issues:
gross margin has fallen
overheads have increased
customer payments are taking longer.
Instead of creating a general goal to “improve profitability”, the business could develop several targeted actions.
Priority 1: Review pricing and margins
Analyse product and service margins and identify areas where pricing no longer reflects costs.
Priority 2: Review overheads
Analyse recurring expenses and identify costs that can be reduced, renegotiated or better controlled.
Priority 3: Improve receivables
Review outstanding invoices, customer payment behaviour and collection processes.
Priority 4: Monitor results
Track gross margin, operating expenses, receivables and cash flow through regular management reporting.
This approach creates a connection between:
Problem → analysis → action → measurement → review.
That connection is what makes an improvement plan useful.
What Is the Difference Between a Business Improvement Plan and a Business Plan?
The terms sound similar, but they serve different purposes.
A business plan generally explains how a business intends to operate and achieve its broader objectives.
It may cover:
business model
target market
products or services
marketing
operations
financial projections
growth objectives.
A business improvement plan is more focused on improving the performance or operation of an existing business.
It may address:
declining profitability
inefficient processes
cash-flow pressure
weak financial controls
underperforming areas
operational problems
performance gaps.
A business plan asks:
“Where are we going and how will we get there?”
An improvement plan often asks:
“What is not working well enough today, and what are we going to change?”
A business may need both.
What Is the Difference Between a Business Improvement Plan and a Strategic Plan?
A strategic plan generally focuses on the business's longer-term direction.
It can cover areas such as:
long-term objectives
competitive positioning
market opportunities
growth
investment
organisational direction.
A business improvement plan can be more immediate and operational.
For example, a strategic objective might be to increase profitability over the next three years.
An improvement plan might address the specific issues currently preventing the business from achieving that objective.
The two can therefore work together.
Strategy establishes direction.
Improvement planning helps address the practical barriers to better performance.
How Financial Information Supports a Business Improvement Plan
Financial information should be more than a record of what happened last month.
It can provide evidence for deciding what needs to improve.
Useful information may include:
profit and loss reports
balance sheets
cash-flow reports
budget-to-actual comparisons
aged receivables
aged payables
gross margins
business KPIs
cost analysis
sales trends.
For example, a business owner might believe that labour costs are the biggest problem.
A review of the financial information may show that labour costs are relatively stable while supplier costs and discounting have had a larger effect on margins.
That changes the improvement priority.
This is why reliable accounting and management reporting are important foundations for effective business improvement.
Common Mistakes When Creating a Business Improvement Plan
A plan can look impressive and still fail to improve the business.
Several problems are common.
Trying to fix everything at once
A long list of initiatives can overwhelm the business.
Focus on the issues that are most important to performance, cash flow, risk or strategic objectives.
Setting vague goals
“Improve operations” is not a measurable action.
A stronger objective identifies what needs to change and how progress will be measured.
Ignoring financial impact
An operational improvement that costs more than it saves may not improve the business.
Consider both the expected benefit and the resources required.
Failing to assign responsibility
Actions without owners are easy to postpone.
Each significant action should have someone responsible for progressing it.
Not setting a review date
A plan needs follow-up.
Without regular reviews, management may not know whether the changes are producing the expected result.
Treating the plan as fixed
Business conditions change.
A customer may leave, costs may increase, market conditions may shift or a new opportunity may appear.
An improvement plan should be updated when circumstances change.
How Long Should a Business Improvement Plan Take?
There is no standard timeframe.
The appropriate period depends on the issue and the complexity of the business.
Some improvements can be implemented quickly.
For example:
changing an approval process
reviewing pricing
improving invoice follow-up
introducing a regular financial review.
Other initiatives may take considerably longer.
For example:
implementing new accounting systems
restructuring operations
changing staffing models
entering new markets
redesigning major business processes.
Rather than choosing an arbitrary timeframe, establish realistic milestones and review progress regularly.
When Should You Get Professional Business Advisory Support?
Business owners can develop improvement plans internally, particularly when the issues are straightforward.
External business advisory support can be useful when:
the problems are difficult to diagnose
financial performance has changed significantly
cash flow is under pressure
several departments are affected
management lacks reliable financial reporting
the business is preparing for major growth
an owner needs an independent perspective
there are competing priorities
improvement initiatives have repeatedly stalled.
An adviser can help bring together financial information, operational considerations and commercial priorities.
The goal is not to take decision-making away from the business owner.
It is to provide better information and structure around those decisions.
How Daintree Consulting Can Help With Business Improvement
Daintree Consulting provides commercially grounded business advisory services for Australian business owners and leadership teams dealing with growth, performance pressure, restructuring and important decisions.
A business improvement process may involve reviewing financial performance, cash flow, KPIs, costs, working capital and other areas affecting the business.
From there, the focus can shift to practical actions and ongoing monitoring.
Depending on your circumstances, this may include:
profitability analysis
financial performance review
cash-flow and working-capital analysis
KPI development
management reporting
budgeting and forecasting
strategic planning
growth planning
business structure and risk considerations
ongoing business advisory support.
If you know your business needs to improve but are struggling to identify where to start, a structured review can help turn the problem into a clearer set of priorities.
Book a free 30-minute discovery call with Daintree Consulting to discuss your business and where advisory support may be useful.
Frequently Asked Questions About Business Improvement Plans
What is the purpose of a business improvement plan?
The purpose is to identify areas where a business needs to improve and establish practical actions, responsibilities, timeframes and measures for addressing them.
When should a business create an improvement plan?
A business may benefit from an improvement plan when profitability, cash flow, operational efficiency or other important performance measures are below expectations, or when the business is undergoing significant change or growth.
Is a business improvement plan only for struggling businesses?
No. Improvement planning can also be useful for healthy businesses that want to improve efficiency, strengthen processes, prepare for growth or address emerging performance issues.
What should a business improvement plan include?
A practical plan can include the current position, key problems, root causes, improvement priorities, actions, responsibilities, timeframes, KPIs and a review process.
How do you measure whether a business improvement plan is working?
The appropriate measures depend on the objectives. They could include profit margins, cash flow, revenue, costs, debtor days, operational KPIs, customer measures or other indicators relevant to the improvement area.
Can an accountant help with a business improvement plan?
An accountant or business adviser can provide financial analysis, reporting and commercial insight that may help identify improvement opportunities and monitor progress. The appropriate support depends on the business's circumstances and the scope of the engagement.
Final Takeaway
A business improvement plan is not about creating more paperwork.
It is about creating a clearer connection between a business problem and the actions needed to address it.
A useful plan identifies:
where the business is now
what needs to improve
why the problem exists
what needs to change
who is responsible
when it should happen
how success will be measured.
For business owners, this can make improvement efforts more focused and easier to monitor.
And importantly, the plan should remain practical.
If the business has reliable financial information, clear priorities and regular performance reviews, management has a stronger foundation for deciding what needs attention and where resources should be directed.
Important Publishing Note: Business improvement planning is highly dependent on the circumstances, structure, objectives and financial position of each business. This article provides general information only and is not a substitute for professional accounting, tax, financial, legal or other advice. Any forecasts, budgets or projections should be based on appropriate assumptions and should not be treated as guarantees of future results.
Talk to Daintree about your next business decision
Our ex-Big 4 team gives clear, senior-reviewed advice so you can act with confidence.
Book a free consultation →
Or explore our business advisory services.
