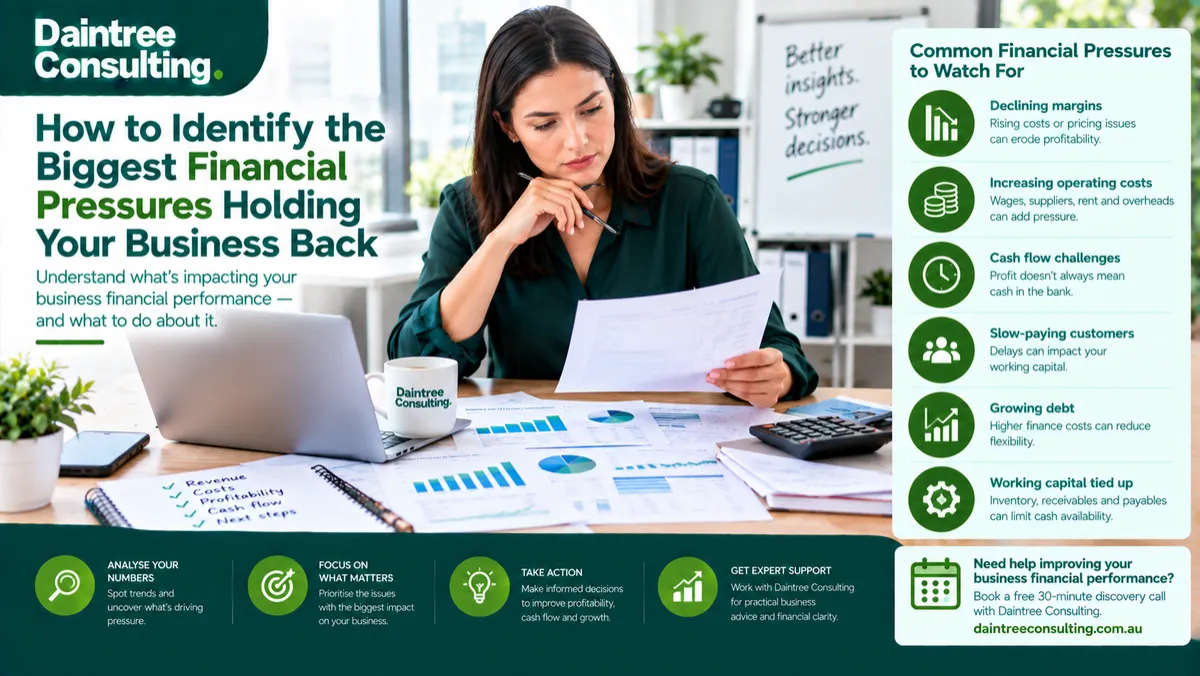
How to Identify the Biggest Financial Pressures Holding Your Business Back
A business can be busy, generate strong revenue and still feel financially stretched.
You may have more customers than ever, but less cash in the bank. Your sales might be increasing, yet profit margins are getting thinner. Payroll may be rising faster than revenue, or customers may be taking longer to pay. You might even be working harder every month without seeing a meaningful improvement in the bottom line.
Want expert help? Daintree Consulting's business advisory services can take this off your plate. Book a free consultation.
These situations are common signs that something is putting pressure on your business financial performance.
The challenge is identifying exactly what it is.
Financial pressure rarely comes from one number alone. It can develop through a combination of rising costs, weak margins, poor cash-flow timing, excessive overheads, inefficient operations, slow receivables or decisions being made without reliable financial information.
The good news is that these pressures can often be identified by looking at your financial information differently.
Instead of asking:
“How much did we sell this month?”
ask:
“Where is the money going, what is changing, and why?”
That shift can give business owners a much clearer view of what is holding the business back.
Quick answer: What are the biggest financial pressures on a business?
The biggest financial pressures often include:
Declining or inconsistent profit margins
Rising wages and employment costs
Increasing supplier and operating costs
Poor cash-flow timing
Slow-paying customers
Excessive overheads
High debt or finance costs
Low productivity
Underperforming products or services
Excess inventory or working capital tied up in the business
Unplanned growth
Weak financial reporting and forecasting
Not every pressure will apply to every business.
The important thing is to identify which pressures are having the largest financial impact on your particular business.
Start with profit, not just revenue
Revenue is one of the easiest numbers for business owners to focus on.
It is also one of the easiest numbers to misunderstand.
A business generating $5 million in annual revenue is not necessarily performing better than a business generating $2 million.
The more important question is what happens to that revenue after the business pays the costs required to generate it.
For example, revenue might increase while:
Gross margins decline
Wages increase disproportionately
Supplier costs rise
Marketing costs increase
Finance costs grow
Overheads expand
Discounts become more common
The result can be a business that looks successful from the outside but is becoming less profitable internally.
This is why reviewing business financial performance should involve more than monitoring sales.
Look at the relationship between:
Revenue → gross profit → operating expenses → net profit → cash flow
Each stage tells you something different.
1. Check whether your margins are under pressure
One of the first places to look is gross margin.
Gross margin shows what remains after the direct costs associated with delivering your products or services are taken into account.
If revenue is increasing but gross margin is falling, you may have a problem that needs attention.
Possible causes include:
Supplier price increases
Discounting
Product mix changes
Higher direct labour costs
Rising freight costs
Increased production costs
Pricing that has not kept up with costs
Delivering more work than originally quoted
Low-margin customers or products becoming a larger part of sales
For service businesses, margin pressure can also occur when staff spend more hours delivering work than the business is charging for.
For example, imagine a project was quoted based on 40 hours of work but ultimately takes 65 hours.
The revenue might look fine.
The margin may not.
That is why business owners should understand profitability at a level that is useful for decision-making — whether that means by product, service, customer, project, location or business division.
2. Look at where your operating costs are increasing
The next step is reviewing operating expenses.
Do not simply look at the total.
Look at what has changed.
Compare your current expenses against:
Previous months
The same period last year
Your budget
Your forecast
Revenue growth
Gross profit growth
A $20,000 increase in expenses might not be concerning if revenue and gross profit have increased significantly.
The same increase could be a serious issue if revenue has remained flat.
Common areas to investigate include:
Payroll
Payroll is often one of the largest expenses for Australian businesses.
Look beyond the total payroll figure.
Consider:
Headcount
Overtime
Contractor costs
Superannuation
Leave costs
Recruitment
Training
Productivity
Revenue or gross profit per employee
Growing payroll can be justified when it supports profitable growth.
The problem is when employment costs rise without a corresponding improvement in output or financial performance.
Premises
Review:
Rent
Utilities
Maintenance
Cleaning
Insurance
Property-related costs
Ask whether the premises are being used efficiently and whether the current cost structure still makes commercial sense.
Technology and subscriptions
Software costs can quietly accumulate.
A business may have dozens of subscriptions covering:
Accounting
CRM
Marketing
Project management
Communications
Cloud storage
Cybersecurity
Design
Productivity
Individually, these may seem insignificant.
Collectively, they can become a meaningful overhead.
Review what you are paying for and whether each system is still being used.
3. Investigate your cash flow separately from your profit
A profitable business can still experience cash-flow pressure.
That is because profit and cash are not the same thing.
For example, a business might record revenue when it invoices a customer, while the customer does not pay for another 30, 60 or 90 days.
Meanwhile, the business still has to pay:
Employees
Suppliers
Rent
Tax obligations
Superannuation
Loan repayments
Other operating costs
This creates a timing problem.
A useful financial review should therefore examine both:
“Are we profitable?”
and:
“Do we have enough cash at the right time?”
If cash flow is becoming increasingly difficult, investigate:
Debtor days
Outstanding invoices
Supplier payment terms
Inventory
Tax obligations
Payroll commitments
Loan repayments
Capital expenditure
Working capital requirements
Cash-flow reporting can help reveal pressure that a profit and loss statement alone may not show.
4. Find out whether customers are paying too slowly
Your sales may be strong, but if customers are taking too long to pay, your business can still feel financially constrained.
Review your accounts receivable regularly.
Look for:
Overdue invoices
Large outstanding balances
Customers consistently paying late
Increasing debtor days
Disputed invoices
Invoices that were never followed up
Customers receiving extended payment terms
A growing debtor balance can absorb significant working capital.
This is particularly important for businesses experiencing rapid growth.
More sales can sometimes create more cash-flow pressure, not less, because the business has to fund the delivery of those sales before receiving payment.
5. Review your pricing
Pricing is one of the most commercially important parts of financial performance.
If your costs have increased but prices have remained unchanged, your margin may be shrinking without an obvious change in sales volume.
Ask:
When did we last review our pricing?
Have supplier costs increased?
Have wages increased?
Has the cost of delivering our service changed?
Are discounts reducing our effective selling price?
Which products or services have the strongest margins?
Which customers are the most profitable?
Are we charging appropriately for additional work?
A business does not necessarily need to raise prices across the board.
But it should understand how pricing decisions affect profitability.
6. Identify products, services or customers that consume resources without producing enough return
Revenue does not always tell you which parts of a business are performing well.
One product might generate $500,000 in sales and produce a strong margin.
Another might generate $700,000 but require substantially more labour, support and overhead.
The second product generates more revenue but may contribute less to the overall result.
The same principle can apply to customers.
Some customers may:
Pay quickly
Purchase regularly
Require limited support
Generate strong margins
Others may:
Negotiate heavily
Require extensive support
Pay late
Generate frequent rework
Require substantial management time
Understanding these differences can help business owners make better decisions about pricing, service levels, resources and customer strategy.
7. Look at working capital
Working capital is another potential source of financial pressure.
Money can become tied up in:
Accounts receivable
Inventory
Deposits
Work in progress
Other short-term operating assets
When too much cash is tied up, the business may need additional funding simply to continue operating.
Consider:
Accounts receivable
How quickly are customers paying?
Inventory
How much stock is sitting on shelves?
Work in progress
How much completed or partially completed work has not yet been invoiced?
Accounts payable
What payment terms do you have with suppliers?
Improving working-capital management does not necessarily mean cutting costs.
Sometimes it means changing the timing of when cash enters and leaves the business.
8. Review debt and finance costs
Borrowing can help a business grow, purchase assets or manage temporary working-capital requirements.
But debt can also create ongoing pressure.
Review:
Loan balances
Interest costs
Repayment schedules
Finance leases
Business credit cards
Overdrafts
Short-term finance
Equipment finance
The question is not simply whether the business has debt.
The question is whether the debt structure remains appropriate for the business's current financial position.
Increasing finance costs can put additional pressure on profit and cash flow, particularly when interest rates or borrowing requirements change.
9. Compare actual performance against the budget
A budget is much more useful when you compare it with what actually happened.
This is where budget vs actual reporting becomes valuable.
For example, suppose your business budgeted:
$1 million in revenue
$400,000 in direct costs
$350,000 in operating expenses
But actual results show:
$950,000 revenue
$430,000 direct costs
$390,000 operating expenses
The issue is not simply that revenue was $50,000 below budget.
There are multiple areas of pressure.
Direct costs were higher.
Operating expenses were higher.
The combined effect could be significantly larger than the revenue variance alone suggests.
The next question should be:
Why?
That is where financial reporting becomes useful.
10. Don't ignore small increases that keep repeating
Financial pressure does not always arrive as one large expense.
It can develop through dozens of smaller increases.
For example:
Software subscription increases
Insurance increases
Supplier price increases
Small wage increases
Additional contractor hours
Higher delivery costs
Increased bank fees
More frequent advertising spend
Each change may seem manageable.
Together, they can materially affect profitability.
A regular management accounts process can help identify these trends before they become significant.
11. Check whether growth itself is creating pressure
Growth is usually considered positive.
But poorly planned growth can put substantial pressure on a business.
Consider a business that wins several large contracts.
Revenue increases rapidly.
The business then needs to:
Hire employees
Purchase equipment
Increase inventory
Lease additional space
Spend more on marketing
Extend customer credit
Increase working capital
Revenue rises, but cash requirements rise too.
This is why businesses should understand the financial requirements of growth before committing to major expansion.
Growth needs to be funded.
12. Review your financial information regularly
One of the biggest obstacles to improving business financial performance is not necessarily poor financial management.
Sometimes it is simply a lack of timely information.
If your financial reports are prepared months after the relevant activity occurred, they are much less useful for making decisions.
Business owners should consider whether they have regular visibility over:
Revenue
Gross profit
Operating expenses
Net profit
Cash position
Accounts receivable
Accounts payable
Working capital
Budget variances
Key performance indicators
Forecast results
The right reporting frequency depends on the size, complexity and needs of the business.
For some businesses, monthly reporting provides a useful rhythm.
For others, more frequent monitoring may be appropriate.
A practical process for identifying financial pressure
You do not need to analyse every financial metric at once.
A practical review can start with five steps.
Step 1: Compare revenue and gross profit
Has revenue increased, decreased or stayed relatively stable?
What happened to gross margin during the same period?
Step 2: Identify the biggest cost movements
Compare current costs against the previous period, prior year and budget.
Highlight significant changes.
Step 3: Review cash flow
Look at cash inflows, cash outflows, debtors, creditors and upcoming commitments.
Step 4: Investigate the cause
Do not stop at identifying a variance.
Ask why it happened.
For example:
Payroll increased.
Why?
Perhaps headcount increased.
Why?
Because sales increased.
Was the additional revenue profitable enough to support the additional employees?
That second layer of questioning is where useful financial analysis begins.
Step 5: Decide what action is required
Not every financial variance requires intervention.
Some are expected.
Others may require:
Pricing changes
Cost control
Better debtor management
Supplier negotiations
Staffing changes
Process improvements
Revised budgets
New funding
Changes to product or service mix
More detailed financial reporting
The goal is to focus attention on the pressures that can materially affect the business.
Financial pressure is easier to manage when you can see it early
One of the biggest advantages of reliable financial reporting is visibility.
You cannot easily respond to a problem you cannot see.
If margins are declining for six months before anyone notices, recovering profitability may be much harder than if the trend had been identified after the first or second month.
Likewise, if debtor days are steadily increasing, the business may have an opportunity to address collection processes before cash flow becomes critical.
This is why management accounts, cash-flow reporting, budgets and KPIs should not be viewed as paperwork created simply for the accountant.
They are decision-making tools.
What should business owners focus on first?
If you are concerned about your financial performance, start with the areas most likely to affect the result.
A useful first review is:
1. Revenue
Is sales growth healthy and sustainable?
2. Gross margin
Are you retaining enough from each sale after direct costs?
3. Operating expenses
Which costs are growing faster than expected?
4. Cash flow
Do you have sufficient cash to meet upcoming commitments?
5. Debtors
Are customers paying within agreed terms?
6. Working capital
How much cash is tied up in the operating cycle?
7. Debt
Are finance costs and repayments manageable?
8. Productivity
Are labour and other resources producing an appropriate return?
9. Pricing
Does your pricing reflect current costs and required margins?
10. Forecast
What is likely to happen over the next three, six or twelve months?
This gives you a more complete picture than looking at revenue or bank balance alone.
When should you get professional financial support?
If your business is experiencing financial pressure but you cannot identify the cause, it may be time to bring in additional financial support.
This can be particularly useful when:
Revenue is growing but cash flow is tightening
Profit margins are falling
Costs are increasing unexpectedly
Financial reports are difficult to interpret
Budgets are not being compared with actual results
You are preparing for significant growth
The business is considering borrowing or investment
Working capital is becoming difficult to manage
You need better forecasting
Management decisions are being made without reliable numbers
The objective is not simply to produce more reports.
It is to turn financial information into practical decisions.
An experienced accounting or business advisory team can help identify the financial drivers behind your results and establish reporting that gives leadership a clearer view of what is happening.
Final thoughts
Strong business financial performance is not simply about generating more revenue.
A financially healthy business needs to understand how revenue converts into gross profit, how costs affect margins, how working capital moves through the business and whether cash flow can support current operations and future plans.
The biggest financial pressures are often hiding in plain sight.
They may be sitting in declining margins, rising payroll, slow-paying customers, excessive overheads, underperforming services or working capital that is tied up for too long.
The key is to identify the pressure early, understand why it is happening and decide what action makes commercial sense.
If your financial reports only tell you what happened months ago, it may be time to improve the way you monitor performance.
Need clearer visibility over your business financial performance?
Daintree Consulting helps Australian businesses turn financial information into clearer reporting and better commercial decisions.
Our accounting and business advisory services can help with management reporting, cash-flow visibility, budgeting, forecasting, KPI analysis and financial performance reviews.
Book a free 30-minute discovery call with Daintree Consulting to discuss where your business is under financial pressure and what information you need to make better decisions.
Frequently Asked Questions
What is business financial performance?
Business financial performance describes how effectively a business generates revenue, manages costs, produces profit and maintains financial stability.
It can be assessed using measures such as revenue, gross profit, profit margins, operating expenses, cash flow, working capital and other relevant financial KPIs.
What are common signs of financial pressure in a business?
Common signs include declining profit margins, increasing expenses, cash-flow shortages, slow-paying customers, growing debt, increasing reliance on short-term finance and revenue growth that does not translate into stronger profitability.
Can a business be profitable but still have cash-flow problems?
Yes.
Profit and cash flow measure different things. A business can record profitable sales while waiting for customers to pay, creating a cash-flow gap between income being recognised and cash actually being received.
Why is gross margin important?
Gross margin shows how much remains from revenue after direct costs are taken into account.
A declining gross margin can indicate issues with pricing, supplier costs, labour, product mix or the cost of delivering products or services.
How often should a business review its financial performance?
The appropriate frequency depends on the business.
Many businesses benefit from monthly management reporting, while businesses with more complex operations or rapidly changing cash flow may need more frequent monitoring of selected metrics.
What financial reports should a business owner review?
A useful management reporting pack may include the profit and loss statement, balance sheet, cash-flow information, budget vs actual results, key performance indicators, accounts receivable, accounts payable and relevant forecasts.
The exact reports should be tailored to the business.
How can I improve my business financial performance?
Start by identifying the biggest drivers of your financial result.
Review margins, pricing, operating costs, cash flow, debtors, working capital and productivity. Once the main pressure points are identified, develop practical actions and monitor whether they improve the result.
Should I focus on reducing costs or increasing revenue?
Neither should automatically be the priority.
The better question is which changes are most likely to improve sustainable profitability and cash flow.
Cutting an expense that contributes to profitable revenue could hurt the business, while increasing sales at very low margins may create additional workload without sufficient financial benefit.
When should a business consider a financial performance review?
A review can be particularly useful when profitability is declining, cash flow is tightening, growth is accelerating, costs are rising or management does not have clear visibility over the numbers.
It can also be useful before major decisions such as expansion, borrowing, investment or restructuring.
Talk to Daintree about your next business decision
Our ex-Big 4 team gives clear, senior-reviewed advice so you can act with confidence.
Book a free consultation →
Or explore our business advisory services.
